Overview:
Wealth management has gone beyond providing traditional investment advice, carrying out portfolio reviews and holding face-to-face meetings. Since financial services are becoming more digital, investors now expect easier access to information, more personalised advice and quicker communication.
Because of this change, wealth managers are adopting digital tools in order to increase efficiency and offer clients a more connected experience. A modern approach to wealth management brings together technology, financial data and professional expertise in order to enable clients to manage their wealth more effectively.
Yet successful digital transformation is not just a matter of introducing more technology; it requires firms to develop an integrated system in which data, advisors and digital services function together.
Start With a Clear Financial Strategy:
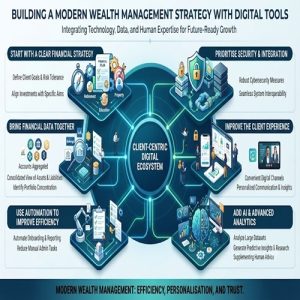
Technology should serve financial goals rather than become the goal itself; a contemporary wealth management approach must start by gaining an understanding of the client’s financial situation, investment objectives, risk tolerance, income needs, and long-term plans. Digital financial planning tools which are digital can assist advisers in gathering and organising this information and, at the same time, give clients a clearer understanding of their financial situation. Digital platforms focused on goals can also be of help in linking investments with specific aims such as retirement planning, the education of children, buying a property or the long-term preservation of wealth.
Bring Financial Data Together:
A significant benefit of digital wealth management is that it allows for a combined view of financial information. Investors have their assets distributed among various accounts, investment platforms, brokers and financial institutions. Digital tools for portfolio management and reporting are able to gather relevant information so that advisors and clients can analyse the entire portfolio rather than examining each investment on its own.
For example, research highlighted by LSEG found that 68% of investors place a value on having a comprehensive view of their assets and liabilities. A connected data environment can also be used to identify portfolio concentration, performance trends and changing financial requirements.
Use Automation to Improve Efficiency:
Wealth management is not an activity that is performed in a single step; there are lots of repetitive administrative tasks, such as onboarding clients, gathering documents, preparing reports, arranging appointments and carrying out compliance procedures. By automating these tasks, manual work can be reduced, and advisors will have more time available to focus on activities which call for human judgement.
Digital onboarding, electronic documentation, automatic portfolio reports and workflow management can lead to more seamless processes for both clients and advisors. This is especially beneficial for firms which are looking after an increasing number of clients without having to increase their administrative complexity by as much.
Add AI and Advanced Analytics:
AI has emerged as an important element of digital wealth management because of its ability to analyse large amounts of information, detect patterns and assist advisors in arriving at relevant insights. AI-powered tools can help with research, communicating with clients, keeping an eye on the portfolio and carrying out routine tasks; emerging agentic AI systems can do even more by keeping watch on predefined conditions and setting off the relevant workflows.
Technology should instead supplement the advisor-client relationship rather than completely replace it, since financial decisions usually involve individual circumstances and priorities which call for context, communication and professional judgement.
Improve the Client Experience:
Investors today expect financial services to be available via convenient digital channels. By using mobile applications, client portals, online meetings and digital communication tools, it becomes easier to access information about their portfolios and to communicate with their advisors. Personalisation is likewise becoming important.
Digital platforms are able to offer relevant insights and services by making use of information about their clients and carrying out analytics, rather than giving every investor the same experience. Examples from the Indian wealth management sector illustrate how data analytics, portfolio aggregation and goal-based investment tools can support more personalised digital experiences.
Prioritise Security and Integration:
The greater extent to which wealth management is digital makes cybersecurity and data protection essential elements of any strategy. Companies must have suitable authentication, access controls, monitoring and governance if they are to protect sensitive financial information. It is just as important to achieve integration.
If systems are not connected, advisors will have to switch among a number of different platforms and transfer the information manually. Nowadays, wealth management technology emphasises on interoperability in order that data may move efficiently between CRM, portfolio, analytics and communication systems.
Build a Future-Ready Wealth Management Model:
Creating a modern wealth management strategy is really all about combining digital capabilities with human expertise; cloud platforms, data analytics, automation, AI and digital client portals can enhance efficiency and personalisation, while advisors keep on giving their advice and context.
The best way to proceed is not just to use more tools but to set up an integrated digital ecosystem which enables more effective data management, smoother operations and more meaningful client relationships. Since technology is still developing, wealth managers who establish flexible, secure and client-orientated digital foundations will be able to adapt more easily to changing investor expectations.
Frequently Asked Questions:
1. What is digital wealth management?
Digital wealth management uses technology, online platforms, and financial software to help individuals manage investments, track assets, plan financial goals, and monitor portfolio performance.
2. How can digital tools improve wealth management?
Digital tools can simplify portfolio tracking, automate routine financial tasks, provide real-time financial insights, and help investors make informed decisions. They can also improve access to investment information and financial planning services.
3. What are the key components of a modern wealth management strategy?
A modern wealth management strategy includes goal setting, asset allocation, risk assessment, portfolio diversification, tax planning, retirement planning, and regular portfolio reviews. Digital tools can support these activities through analytics, automation, and consolidated financial reporting.
4. How does artificial intelligence support wealth management?
Artificial intelligence can analyse financial data, identify investment patterns, assess potential risks, and generate personalised financial insights. It can also support portfolio monitoring and automate selected investment processes, depending on the platform.
5. What role do robo-advisors play in digital wealth management?
Robo-advisors use algorithms to recommend or manage investment portfolios based on factors such as financial goals, investment horizon, and risk tolerance. They can make portfolio management more accessible and automate tasks such as asset allocation and rebalancing.
6. How can investors use digital tools to manage investment risks?
Investors can use digital tools to monitor asset allocation, assess portfolio concentration, track market movements, and review performance against financial goals. These tools support risk management but cannot eliminate investment losses or predict market movements with certainty.
7. Are digital wealth management platforms suitable for beginners?
Yes. Many digital wealth management platforms offer accessible dashboards, investment tracking, goal-setting tools, and educational resources. Beginners should compare fees, understand investment risks, and check the provider’s credentials before choosing a platform.
8. How does data analytics help with wealth management decisions?
Data analytics helps investors and wealth managers evaluate portfolio performance, understand financial trends, assess risk exposure, and compare investments. These insights can support better-informed decisions when combined with suitable financial objectives and professional judgment.
9. What are the challenges of using digital tools for wealth management?
Common challenges include cybersecurity threats, data privacy concerns, integration with existing financial systems, technology costs, and the risk of relying too heavily on automated recommendations. Choosing reputable platforms and maintaining appropriate human oversight can help address these issues.
10. What is the future of digital wealth management?
Digital wealth management is likely to expand through AI-powered financial insights, automated portfolio management, personalised investment services, and integrated financial planning platforms. Greater adoption will depend on data security, regulatory compliance, transparency, and investor trust.