Introduction:
Decentralised finance (DeFi) was first linked with crypto users, decentralised exchanges and open lending platforms.. The technology behind it is now being looked at more closely by banks, money managers and companies. Institutional DeFi takes DeFi ideas. Brings them into the world of regulated finance by using blockchain automation along with checks for identity, rules, keeping safe and managing risk.
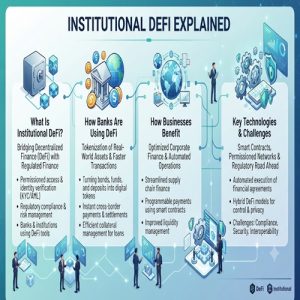
What Is Institutional DeFi ?
Institutional DeFi means that banks, financial companies, money managers and businesses use the tools of finance for tasks like lending, borrowing, sending money, settling deals, trading and managing assets.
Unlike DeFi, where people often use their own wallets to talk directly to systems, institutional use usually adds more rules. These might include checking who is using the system, who is allowed to take part, keeping money safe, setting limits on what can be done and making reports.
The goal is not always to take the place of finance. Instead, companies are looking at how blockchain and smart contracts can make existing financial work faster, clearer and easier to handle.
How Banks Are Using DeFi ?
One area is turning real assets into digital form. Banks and financial companies can turn things like bonds, funds, deposits and other physical assets into tokens. These tokens can then be handled on blockchain networks.
A report from 2026 shows that more and more companies are trying out blockchain for making, settling and keeping assets, including investment products.
Banks are also looking at blockchain for sending money across borders and handling money matters. For instance, special blockchain systems are being made to support deposits and continuous money management. Digital services deployed by banks is one example of how blockchain’s being used in the banking world.
Another area is handling security for loans. Digital assets can move between people faster, which can cut down on the delays that come with ways of checking and settling.
How Businesses Can Benefit ?
Businesses can use institutional DeFi to perform some financial tasks. Sending money across borders is one example, especially when old systems have middlemen and take too long.
Firms can also try using cash, digital assets and blockchain-based loan systems to handle money better. Smart contracts can do tasks automatically like sending money when certain things happen.
Tokenising can make some financial things easier to move. Could help with splitting ownership. UBS, for example, says that digital financial products are a way to bring assets onto blockchain while still following the rules.
The Role of Smart Contracts:
Smart contracts are key to institutional DeFi. These are computer programs on the blockchain that do actions when certain things happen.
For banks and other financial companies, this can mean work done by people in tasks like settling deals, moving securities, and handling loans. It can also create a shared record of what happened that everyone involved can check.
Smart contracts don’t remove all the risks. Problems in the code, big changes in prices, and issues with how things work and the rules that must be followed still need to be handled.
Permissioned and Hybrid DeFi:
Institutional DeFi does not always mean that anyone can join. Many companies like permissioned or mixed models, where only certain people or groups are allowed to take part.
The IMF says that banks have often liked permissioned networks because they offer control over privacy, making sure things are right handling more work and keeping costs lower. Some companies are now trying permissionless networks with some rules, like allowing certain people.
This mixed way can use the benefits of blockchain, like being able to write rules and being open while also following the rules needed in the world of finance.
Challenges and the Road Ahead:
Institutional DeFi still has problems involving the rules that must be followed, keeping things safe, making different systems work together, keeping things private, and making sure there is money to use and how decisions are made. Financial companies also need to figure out how digital systems can work with banking systems.
The path is becoming clearer. Institutional DeFi is going from ideas to uses, with digital assets sending money, loans and settling deals. As banks and companies keep trying these ideas, DeFi may become less about taking the place of finance and more about making the systems behind it better.
Frequently Asked Questions:
1. What is institutional DeFi?
Institutional DeFi refers to the use of decentralised finance technologies by banks, financial institutions, and businesses. It can involve blockchain-based lending, digital asset management, tokenised assets, and smart contract-powered financial transactions.
2. How is institutional DeFi different from traditional DeFi?
Traditional DeFi generally provides blockchain-based financial services through decentralised protocols that are accessible to individual users. Institutional DeFi focuses on the needs of organisations, including regulatory compliance, risk management, privacy, identity verification, and operational controls.
3. How are banks using decentralised finance?
Banks can explore DeFi technologies for tokenised asset transactions, blockchain-based settlement, digital asset custody, and automated financial processes. The specific applications depend on regulatory requirements, institutional risk policies, and the blockchain infrastructure used.
4. What are the benefits of institutional DeFi for businesses?
Institutional DeFi can support faster settlement, greater transaction transparency, automated financial workflows, access to tokenised assets, and potentially more efficient cross-border transactions. Actual benefits depend on the protocol, implementation, and business requirements.
5. What role do smart contracts play in institutional DeFi?
Smart contracts are programs deployed on blockchain networks that execute predefined instructions when specified conditions are met. In institutional DeFi, they can automate activities such as lending operations, collateral management, asset transfers, and transaction settlement.
6. What is the role of tokenisation in institutional DeFi?
Tokenisation represents ownership rights or interests in assets as digital tokens on a blockchain. In institutional DeFi, tokenisation can support the digital representation and transfer of assets such as bonds, funds, and other eligible financial instruments, subject to applicable legal requirements.
7. Is institutional DeFi secure for banks and financial institutions?
Institutional DeFi can incorporate security measures such as smart contract audits, permission controls, secure digital asset custody, identity verification, and transaction monitoring. However, risks remain, including software vulnerabilities, cyberattacks, liquidity issues, and operational failures.
8. What are the main challenges of institutional DeFi adoption?
Major challenges include regulatory uncertainty, compliance requirements, smart contract vulnerabilities, integration with legacy systems, liquidity constraints, and the complexity of managing digital assets. Institutions must assess these risks before adopting DeFi solutions.
9. How does institutional DeFi support regulatory compliance?
Institutional DeFi platforms can incorporate identity verification, transaction monitoring, permissioned access, audit trails, and compliance checks into financial workflows. These features can support compliance processes, but they do not automatically guarantee adherence to every applicable regulation.
10. What is the future of institutional DeFi?
Institutional DeFi may expand through tokenised financial assets, blockchain-based settlement, regulated digital asset services, and improved integration between traditional finance and decentralised protocols. Its growth will depend on regulatory clarity, security, interoperability, and institutional confidence.